Buying a car — whether from a main dealer, used car forecourt, or independent seller — is an exhilarating experience. You’ve likely spent considerable time comparing models, scrutinising history reports, and ensuring everything aligns with your expectations. But just as you’re ready to drive away, you spot it: A windscreen chip. This is where understanding your windscreen insurance repair becomes crucial. Familiarising yourself with windscreen insurance repair can save you significant time and money in the long run, as proper knowledge will empower you to navigate the complexities of insurance claims effectively. When it comes to windscreen insurance repair, being informed is key.
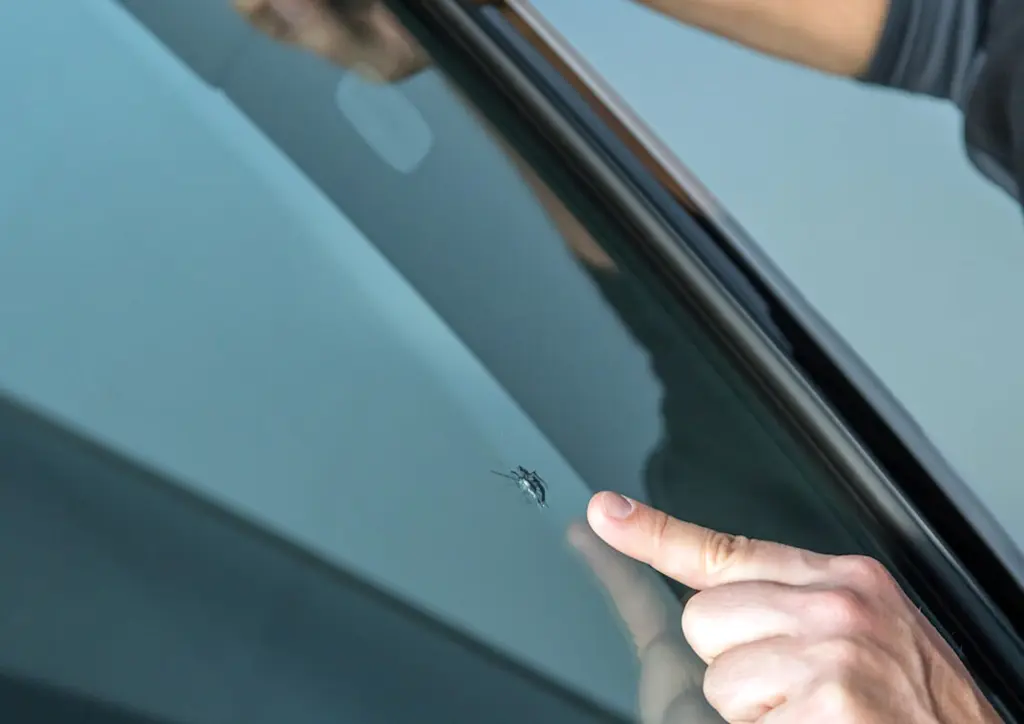
A windscreen chip.
Addressing windscreen damage promptly is essential to maintaining the integrity and safety of your vehicle. A quick repair can prevent further issues, allowing you to enjoy your new vehicle without worry. It’s important to understand the potential implications of neglecting such damage, which can lead to larger problems and additional expenses down the line.
Additionally, understanding your windscreen insurance repair options can aid in ensuring your vehicle is roadworthy.
You point it out, and the salesperson says something like:
“Just claim it on your insurance once you’ve got the car. We’ll pay the excess.”
This is usually said casually and with good intentions. Often, the dealer simply wants to avoid delay or genuinely believes this is how people handle windscreen issues. But even when suggested innocently, this advice can cause problems.
Here’s why it matters — and what you should do instead.
🚗 Why Dealers Sometimes Suggest Using Your Insurance
It’s rarely an attempt to dodge responsibility. Most of the time, it happens because dealers are keen to ensure a smooth and speedy handover process. Furthermore, many dealers believe that the customer can easily manage the windscreen claims process without complications.
Moreover, a timely windscreen insurance repair can significantly enhance your driving safety.
Understanding Windscreen Insurance Repair
1. They want to avoid delaying the handover
Repairing a chip is indeed a quick process, often taking less than an hour, but windscreen replacement (particularly when advanced driver-assistance systems [ADAS] calibration is involved) can take much longer. Dealers aim to keep customers satisfied and happy by avoiding any delays in the handover of the vehicle.
2. They think windscreen claims are “no big deal”
It’s a common misconception that windscreen claims don’t matter. Many people genuinely believe insurers don’t mind.
Being proactive about windscreen insurance repair not only protects your vehicle but also helps manage your insurance costs.
Many customers feel reassured by the idea that their insurance can cover windscreen repairs, assuming that it’s a straightforward and hassle-free process. However, the reality is often more complicated, as they may not fully grasp the implications of making a claim and how it may affect their premiums in the future.
Understanding how windscreen insurance repair works ensures you won’t face any unwelcome surprises.
3. They don’t realise pre-existing damage can’t be claimed
Dealers aren’t insurance experts. They often don’t understand that insurance only covers damage that happens after a customer becomes the policyholder.
So while the intention is usually helpful, the impact isn’t.
Furthermore, making an insurance claim for a windscreen issue can sometimes trigger a series of unfortunate events, such as an increase in your insurance premium upon renewal. Insurers tend to view claims, regardless of their size, as an indicator of risk, which may lead to higher costs for the policyholder in the long run.
⚠️ Insurance Only Covers Damage That Happens While You Own the Car
This is the key point.
This is particularly important in the context of windscreen insurance repair, as many owners overlook the specifics.
This critical point cannot be overstated, as it outlines the parameters within which insurance companies operate. They are designed to mitigate risks associated with events that are sudden and unexpected, which is why pre-existing damage falls outside these parameters.
Insurance companies cover sudden, unexpected damage that happens during the period you are insured.
For example, if a chip or crack has been present before the car legally became yours, the implications are significant:
If a chip or crack was already present before the car legally became yours:
-
- It didn’t occur during your policy
- It wasn’t your loss
Moreover, it’s important to recognise that making a claim for something that is deemed pre-existing could not only complicate your current situation but also impact your future interactions with the insurer. They may flag your account for scrutiny, potentially affecting future claims.
For this reason, clarifying any doubts about windscreen insurance repair before making a claim is essential.
- It’s classed as pre-existing damage
- It cannot be claimed on your insurance
Even if the dealer pays the excess, the claim would still be recorded under your name, your policy, and lead to your record being affected.
This is where complications begin.
Understanding the nuances of insurance claims becomes especially crucial when considering the situation where the same insurer covered the previous owner. This scenario is relatively common, particularly for cars bought from dealerships or auctions. Awareness of these intricacies can help you make informed decisions regarding your claims.
🔍 Extra Complication: When the Same Insurer Covered the Previous Owner
This situation is more common than you might think.
If your new policy and the previous owner’s policy are both with the same insurer, then:
- Insurers often keep vehicle‑specific notes using the registration number
- They may already have photos or reports of the chip
- They might have recorded that damage under the previous policy
So when a new claim arrives shortly after you take ownership, the system could:
- Flag it as pre-existing
- Trigger an automatic review
- Delay or decline the claim
As a result, it’s essential to approach such claims cautiously. This is yet another reason it’s safer not to claim when faced with pre-existing damage. You should always aim to fully assess the condition of your vehicle before finalising your purchase to avoid unexpected complications down the road.
Thus, always weigh the implications of windscreen insurance repair claims carefully.
This is yet another reason it’s safer not to claim.
📋 What Happens If You Try to Claim for Pre‑Existing Damage?
Even if done innocently, a claim for pre‑ownership damage can:
Claims for pre-ownership damage can have far-reaching consequences that may not be immediately apparent. Not only do they impact your current policy, but they can also have implications for new policies in the future. This makes it imperative to understand the risks associated with making such claims.
❌ Be rejected
❌ Lead to questions or delays
❌ Create notes on your policy record
❌ Affect future claims
❌ Leave you paying the repair or replacement yourself
And this can become significantly more costly if the chip has already progressed into a crack requiring a full windscreen replacement. The longer you wait to address the issue, the more difficult and expensive it may become, making timely repairs not just advisable but essential.
In summary, being knowledgeable about windscreen insurance repair can help mitigate future issues.
In conclusion, understanding the intricacies of windscreen insurance repair is vital for every vehicle owner. By being informed, particularly about windscreen insurance repair, you can ensure that your vehicle remains in good condition while avoiding unnecessary complications with your insurance provider. Always remember to inspect your vehicle thoroughly and consult with experts if you find any damage, as this proactive approach to windscreen insurance repair can save you both time and money in the long run.